 By Admin
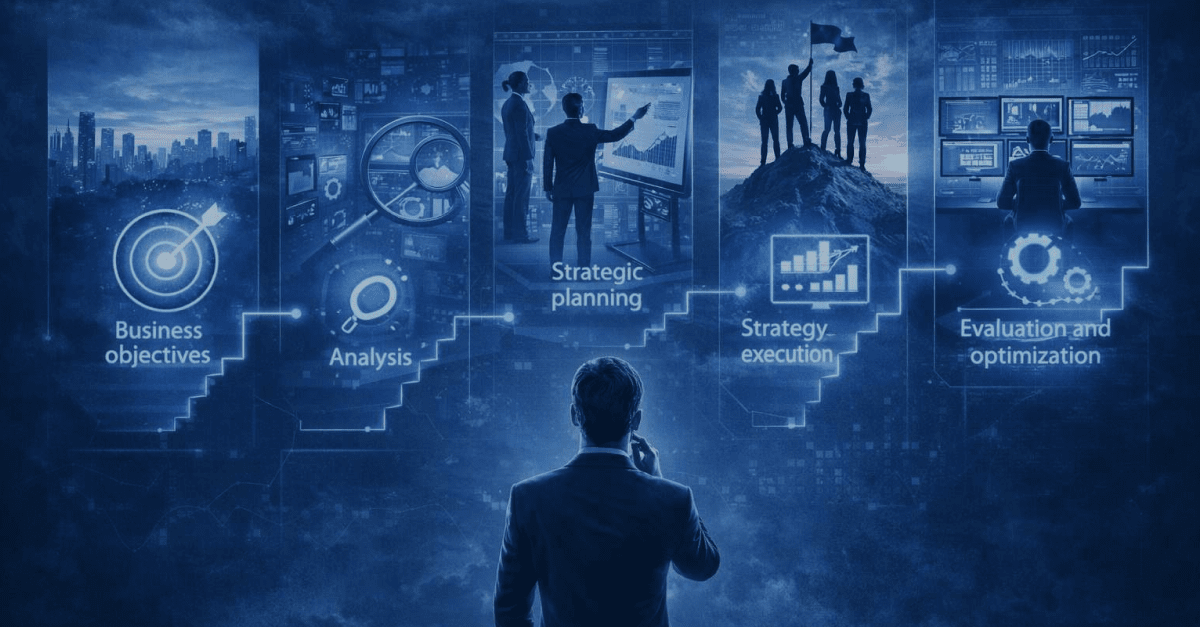
Building long-term financial success requires more than simply saving money or choosing popular investments. Every individual has different goals, responsibilities, risk preferences, income sources, and expectations for the future. A strategy that works well for one investor may be completely unsuitable for another. This is why customized wealth strategies have become an important part of thoughtful financial planning.
A personalized approach considers the complete financial picture rather than focusing on a single investment or short-term market opportunity. By aligning financial decisions with individual circumstances, investors can create a more structured path toward long-term stability, growth, and financial confidence.
Personalized wealth management begins with understanding the investor. Financial goals can vary significantly. One person may prioritize retirement income, while another may be focused on building a business, funding education, purchasing property, or leaving a legacy for future generations.
A customized strategy brings these objectives together into a coordinated financial plan. Instead of following generic recommendations, investors can evaluate their specific circumstances and determine how saving, investing, taxes, insurance, estate planning, and cash-flow management fit together.
This comprehensive approach can also make financial decisions easier to evaluate. When every recommendation connects to a defined objective, investors are better positioned to understand why a particular financial decision may be appropriate for their situation.
Markets often provide countless investment choices, but selecting investments without considering personal circumstances can create unnecessary challenges. Two people with similar incomes may have very different financial needs because of their age, family responsibilities, debt levels, investment horizons, and tolerance for market fluctuations.
For example, an investor with decades before retirement may have different priorities from someone who is already relying on investment assets for income. Similarly, a business owner may face financial considerations that do not apply to a salaried employee.
Customized wealth strategies account for these differences. The objective is not simply to pursue the highest possible return but to create an approach that balances potential growth with appropriate levels of risk and liquidity.
Investment decisions are most effective when they are connected to clearly defined goals. A personalized strategy can help determine how different assets may contribute to objectives over various time horizons.
Long-term investors may consider diversification across different asset categories rather than relying heavily on one investment. Diversification can help manage concentration risk while allowing a portfolio to pursue growth opportunities.
Asset allocation is another important consideration. The appropriate mix of investments can change as financial circumstances and goals evolve. Regular reviews allow investors to assess whether their portfolios continue to reflect their objectives and risk tolerance.
The key is maintaining a disciplined approach rather than making decisions based solely on short-term market movements.
Financial success is not only about growing wealth; it is also about protecting it. Unexpected expenses, market declines, changes in income, inflation, and other financial challenges can affect long-term plans.
A customized wealth strategy considers potential risks and identifies ways to prepare for them. This may involve maintaining appropriate liquidity, reviewing insurance coverage, diversifying investments, or establishing contingency plans.
Risk tolerance should also be distinguished from risk capacity. An investor may feel comfortable with significant market fluctuations but may not have the financial capacity to withstand substantial losses. A thoughtful plan considers both emotional comfort and actual financial circumstances.
Taxes can significantly influence long-term wealth accumulation. Investment returns are important, but the amount ultimately retained after taxes also matters.
Personalized financial planning can incorporate tax considerations when evaluating investment accounts, income strategies, charitable giving, and asset transfers. The appropriate approach depends on individual circumstances and applicable tax rules.
Tax planning should not be viewed as a one-time activity. Financial circumstances can change, and tax laws may evolve. Reviewing strategies periodically can help investors identify opportunities to improve overall financial efficiency.
Retirement planning is one of the clearest examples of why customization matters. Retirement may last for decades, requiring careful consideration of income, expenses, investments, healthcare costs, inflation, and longevity.
A personalized retirement strategy can help investors estimate future needs and determine how current savings and investments may support those objectives. It can also consider when and how assets might be accessed during retirement.
Rather than relying on a simple savings target, investors can build a broader framework around their desired lifestyle and anticipated financial responsibilities.
Many investors seek professional guidance when their financial situations become more complex. Working with an experienced financial professional can provide an additional perspective when evaluating investment decisions, retirement planning, wealth preservation, and other financial priorities.
For individuals researching financial professionals or firms, resources associated with names such as Thomas Kane Merrill Lynch may appear during their search. Investors should independently review any professional’s credentials, services, experience, fees, and regulatory information before establishing an advisory relationship.
The most important consideration is whether the financial professional understands the investor’s objectives and can provide an approach appropriate to those circumstances. Good financial planning should be based on clear communication, transparency, and an understanding of the client’s broader financial picture.
A wealth strategy should not remain unchanged forever. Life can introduce significant changes that affect financial priorities. Career transitions, marriage, divorce, children, business ownership, inheritance, relocation, or changes in retirement expectations can all influence financial planning.
Market conditions can also change. While investors cannot control markets, they can review whether their financial strategies remain appropriate.
Regular portfolio and financial-plan reviews provide an opportunity to evaluate progress, identify changes, and make adjustments when necessary. This flexible approach helps ensure that the strategy remains connected to current circumstances rather than outdated assumptions.
Customized strategies are valuable because they encourage investors to think beyond immediate market performance. Long-term wealth creation generally requires patience, consistency, appropriate diversification, and disciplined decision-making.
Investors may experience periods of strong market growth as well as significant volatility. A well-designed financial strategy provides a framework for making decisions during both favorable and difficult conditions.
Instead of reacting emotionally to every market movement, investors can return to their financial objectives and evaluate whether their overall plan remains appropriate. This can help support more consistent decision-making over time.
Long-term financial success is ultimately about more than accumulating assets. It involves creating a financial structure that supports personal goals, manages risks, prepares for future needs, and provides flexibility when circumstances change.
Customized wealth strategies matter because financial lives are rarely identical. A personalized approach can connect investments, retirement planning, tax considerations, risk management, and wealth preservation into a coordinated framework.
Whether investors are beginning their financial journey or managing substantial accumulated wealth, thoughtful planning can help them make decisions with greater purpose. By regularly reviewing goals and adapting strategies as circumstances evolve, investors can create a more resilient foundation for their long-term financial future.